On this page
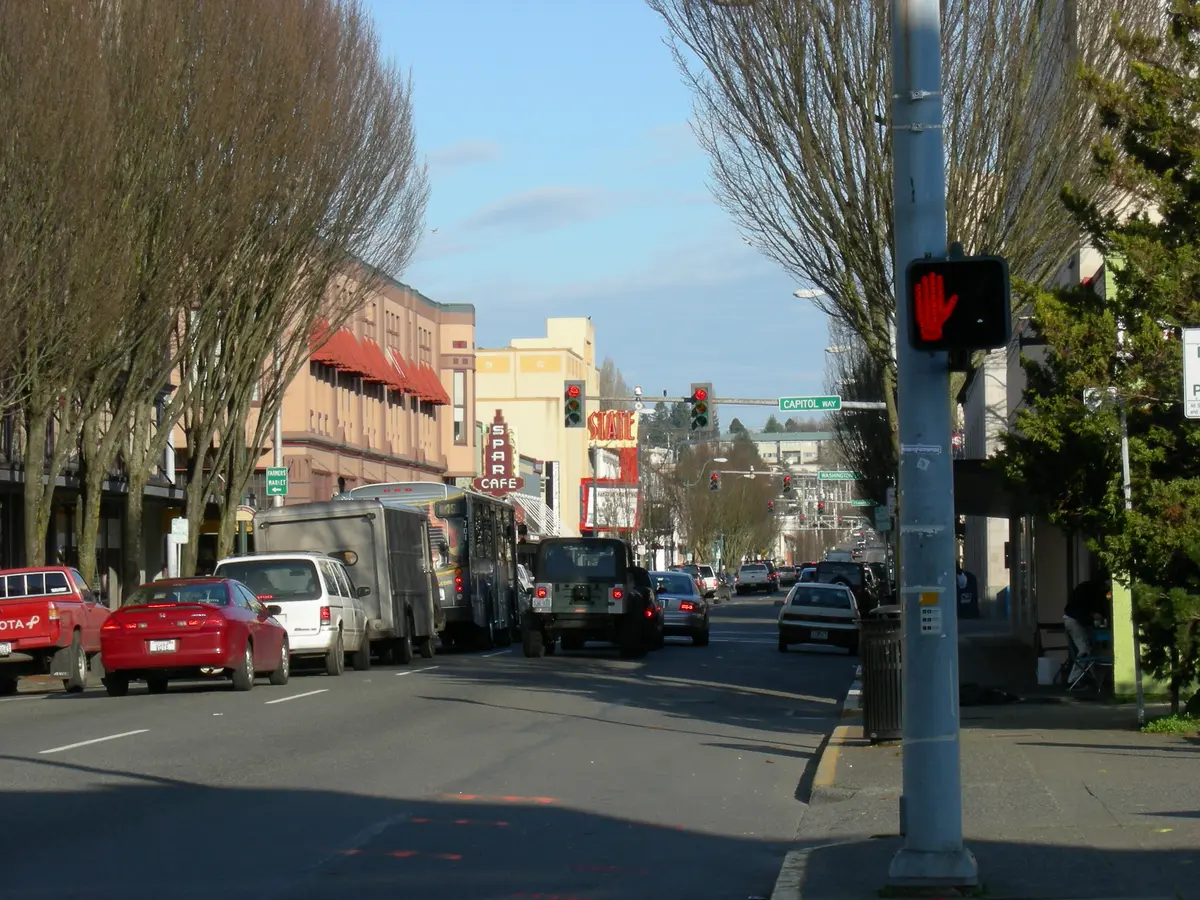

Olympia Car Insurance Made Simple
Olympia drivers comparing car insurance should begin with actual vehicles, regular drivers, overnight garaging and annual mileage. Washington’s general liability minimums are 25/50/10 for applicable vehicles, with approved alternatives and specific vehicle exceptions. This guide explains coverage choices for changing commutes, shared family cars, vehicle purchases and transportation after a covered loss.
Common situations that bring Olympia residents to this page include switching from a daily commute to a hybrid or remote arrangement, adding a young driver to a shared vehicle, buying or financing a car from a local dealer, or figuring out transportation while a vehicle sits at a body shop after an accident. Each of these life changes can affect your policy, your costs, and the protection available to your household.
WashingtonCarInsurance.com, operated by Drivers Insurance Agency, Inc., provides personal auto assistance by phone and online. Request a quote or call 844-348-1313 to discuss your Olympia household’s coverage questions.
Why Olympia Drivers Choose WashingtonCarInsurance.com
Use WashingtonCarInsurance.com to review personal auto requirements and prepare coverage comparisons. Describe your actual driving, household vehicle access and any SR-22 need. A request does not bind coverage; confirm acceptance and the exact effective date before relying on a policy. This guide does not establish an Olympia walk-in office.
WashingtonCarInsurance.com is not affiliated with any government agency. Availability, underwriting, and pricing always depend on insurer approval.
Local-Focused Benefits for Olympia Drivers
Include trips within Olympia and toward other destinations in your mileage estimate. Explain changes in regular drivers, overnight garaging or work activity. A particular route, road project or weather condition alone does not establish your premium or guarantee coverage for a loss.
The site supports situations common in Olympia households-mixed in-office and remote work schedules, families with teen drivers, downtown parking challenges, and seasonal visitors. If you want to talk through coverages and next steps with a person, you can call 844-348-1313 to reach the team directly.
How Olympia Car Insurance Rates and Quotes Are Built
Car insurance rates in Olympia are shaped by Washington state rules, but the price you pay depends on your individual driver profile and the insurer’s underwriting. This section explains the factors behind your premium-not guaranteed prices or averages.
Key Rating Factors for Olympia Drivers
Insurers weigh several variables when building a quote. Here are the most significant:
-
Driving record and claims: Insurers may consider driving history and prior claims under their rules. Record-retention periods and insurer rating periods are different questions; confirm what information is used for your application.
-
Garaging: Give the actual address where each vehicle is principally kept. Location can affect rating and eligibility, but a ZIP code alone does not determine your price. Do not use an address where the vehicle is not actually garaged to obtain a different quote.
-
Vehicle details: Make, model, year, safety features, and theft risk all matter. Vehicles with advanced safety equipment may qualify for lower premiums.
-
Annual mileage and use type: Commuting, pleasure, and business classifications affect rates differently. Low mileage generally corresponds to lower risk.
-
Prior insurance: Explain current coverage and any gaps accurately. Ask how an insurer treats the history for your specific application rather than assuming every company applies the same rule.
-
Credit history: Washington permits insurers to use credit information subject to restrictions. The OIC credit and insurance guide explains the rules. A particular credit history or clean driving record does not guarantee the lowest premium.
Each company weighs these factors differently, which is why drivers in similar situations can still get different rates based on ZIP code and driver profile. To find the best value, compare quotes with matching liability limits, deductibles, and optional coverages when you shop.
Why Commute and Remote Work Patterns Matter
If a household changes between office, hybrid and remote work, calculate the resulting annual driving instead of assuming it decreases. Include school, errands, caregiving and weekend travel alongside the commute.
For a household using transit, vanpools or carpooling more often, describe the remaining vehicle use and who has regular access. Ask the insurer how the actual mileage and use affect a proposal. A schedule change does not guarantee a discount or different rating category.
The key step: notify your insurer when your regular work schedule, commute distance, or parking location changes. Misreporting usage-for example, being rated for “pleasure” when you’re actually commuting daily-can cause rating disputes and problems at claim time.
Washington Minimum Requirements for Olympia Drivers
Washington’s general liability requirements apply to covered vehicle categories across the state. Liability for a crash depends on the facts and applicable law. Review both legal requirements and the protection you would retain under each proposed policy.
Liability Insurance: 25/50/10 and Alternatives
Washington requires minimum liability coverage of 25/50/10 for most private passenger vehicles:
-
$25,000 bodily injury per person
-
$50,000 bodily injury per accident
-
$10,000 property damage per accident
A hypothetical covered property-damage loss of $30,000 leaves $20,000 above a $10,000 limit. Compare higher liability limits with the quoted premium and potential costs above them. No limit guarantees payment of every loss.
Washington DOL lists qualifying bonds or certificates of deposit of at least $60,000, self-insurance for qualifying owners of 26 or more vehicles, and specific vehicle exceptions. Vehicles registered in another state follow that state’s insurance laws.
Personal Injury Protection (PIP) for Olympia Households
Personal Injury Protection covers medical expenses and certain related costs-like lost income and funeral expenses-for covered people regardless of fault, subject to policy terms. In Washington, insurers must offer PIP; it is added and charged unless the named insured rejects it in writing.
The minimum PIP medical benefit is $10,000 for covered expenses incurred within three years. Other benefits have separate limits, waiting periods and conditions; that medical time period does not apply to all benefits. Compare PIP with other protection using the OIC PIP guide.
Uninsured/Underinsured Motorist (UM/UIM) in Washington
UM/UIM may address specified covered losses caused by an uninsured or underinsured motorist. It does not guarantee payment for every hit-and-run; reporting, evidence and other policy or statutory conditions may apply.
Under Washington’s UM/UIM statute, bodily-injury limits generally match liability unless reduced or rejected in writing as permitted. Property-damage coverage is separate, with its own limits, deductibles and conditions. Review the actual written selections.
Compare the protection available at different UM/UIM limits and the amount you could retain after a covered loss. Understand what a reduction or rejection gives up before signing it.
Official Resources for Washington Drivers
These official links help Olympia drivers confirm up-to-date state rules:
-
Washington DOL – Mandatory Insurance Requirements (25/50/10 law, proof, alternatives)
-
Washington OIC – How Auto Insurance Works (UM/UIM, PIP, and general consumer education)
Core Olympia Car Insurance Coverages
Meeting the law is one thing. Protecting your car and household finances is another. Beyond Washington’s minimums, there are coverages that fill gaps-especially when you’re financing a vehicle, sharing cars in a household, or dealing with a suspended license.
Liability Limits Beyond the Minimum
Higher liability limits can reduce the amount above a policy limit after a covered serious loss, but they do not eliminate all potential out-of-pocket costs. Consider household circumstances, regular drivers and potential liability when comparing proposals.
Ask for equivalent proposals at more than one liability limit. The premium difference depends on the insurer and application; do not assume a fixed or modest increase for every household.
“Full Coverage”: Collision and Comprehensive
“Full coverage” is an informal phrase-policies actually list liability, collision, comprehensive, and other options separately.
-
Collision may address a covered crash or upset, subject to terms, exclusions and a deductible.
-
Comprehensive may address specified theft, vandalism, fire, falling objects, glass damage or animal strikes, subject to terms, exclusions and a deductible.
Most lenders on Olympia vehicle purchases require both collision and comprehensive until the loan is paid off or the lease is returned. For older, paid-off cars, drivers can decide whether to insure the vehicle for collision and comprehensive based on the car’s value, deductible, and potential premium savings. Visit Washington minimum coverage for a deeper comparison of state-minimum versus broader coverage.
Coverage for Shared Household Vehicles
Many Olympia households share vehicles-partners using one car, adult children moving back home, or roommates occasionally borrowing a vehicle. Accurately listing all household members and regular drivers on your policy is essential.
Unlisted regular drivers or undisclosed household vehicles can cause coverage problems at claim time. Students away at college, or adult children visiting seasonally, may have special rating or eligibility rules depending on the insurer. When in doubt, update your insurer rather than risk a denied claim.
SR-22 Filings for Olympia Drivers
An SR-22 is a filing from an insurer to the Washington Department of Licensing proving you carry at least the required liability limits. It is not a type of insurance and does not grant driving privileges by itself-DOL decides when a license can be reinstated.
Washington DOL generally requires SR-22 proof for about three years from the date a driver is eligible to reinstate, though DOL determines individual requirements and time frames. If the SR-22 coverage lapses during that period, DOL may suspend the license again. Cancelling the policy early has real consequences.
Visit SR-22 guide for more detail and quote-request instructions.
Non-Owner Car Insurance in Olympia
Non-owner coverage may fit eligible occasional borrowers or renters who do not own a vehicle or have regular household-car access. Disclose car-sharing, employer vehicles and regular access for specific review. Eligibility and terms vary by insurer.
Non-owner coverage generally does not pay for damage to the borrowed or rented vehicle. Check that protection separately; an owner’s policy, rental arrangement or credit-card benefit is not guaranteed to cover every driver or loss. Some insurers support SR-22 filings on eligible non-owner policies.
Learn more and request a quote at non-owner coverage.
Olympia Roads, Street Conditions, and Why They Matter
Use official road information for travel planning and keep mileage or use accurate when your routine changes. A pavement condition or project listing alone does not establish a premium or guarantee coverage.
How Olympia Manages Pavement and What It Means for You
The City of Olympia street-condition dashboard explains how pavement inspections help plan preservation, resurfacing and reconstruction. It describes treatments such as chip seal and asphalt overlays.
A historical project example is not a current closure notice. Check the city’s latest information before planning a trip, and follow posted road controls. Do not assume a particular treatment creates an insurance requirement or proves how a future claim will be handled.
Using Olympia’s Project Hub Before You Drive
The City of Olympia maintains a project hub at engage.olympiawa.gov where residents can check for information about upcoming transportation and public works projects. Reviewing project updates before a commute or errands helps you plan routes and avoid last-minute detours.
Current notices can help you plan routes. They do not guarantee an open road, a shorter trip or an insurance discount. Review coverage based on actual vehicle use and the losses addressed by each policy.
Insurance Planning for Changing Commutes and Life Events
Life in Olympia changes. Your car insurance should change with it. Here’s a practical checklist for the most common transitions.
Switching Between Office, Hybrid, and Remote Work
A different work schedule can change annual mileage. Calculate actual trips and notify the insurer of required updates when you:
-
Stop commuting daily to downtown Olympia, Lacey, or other regular destinations
-
Start using rideshare, vanpools, or transit for part of the week
-
Move from a traditional commute to fully remote status
Keep required mileage, garaging and use information accurate. Explain delivery, rideshare or other work activity separately from commuting because a personal policy may restrict some business uses.
Buying or Financing a Car in Olympia
Before buying, review applicable legal liability requirements and any lender or lease conditions. Request coverage for the exact vehicle, confirm how the lender should be listed, check deductible restrictions and obtain acceptance and the effective date before driving away.
Compare coverage options and deductibles before signing loan paperwork-not under pressure in the dealer finance office. Visit buying and financing guide for step-by-step guidance.
Managing Transportation During Repairs
Rental reimbursement coverage helps pay for a rental car while a covered claim repair is in progress, subject to daily and maximum limits. For Olympia drivers whose vehicle is at a local body shop, this coverage can be the difference between getting to work and being stranded.
Plan essential work, school and caregiving trips if a vehicle is unavailable. Check rental reimbursement’s covered-loss trigger, daily and total limits, and end date. It may not cover every expense or the full repair period. See the claims and deductible guide.
Teen Drivers and Shared Family Cars
Before a teen begins driving a shared vehicle, ask the insurer when and how the permit and licensed-driver stages must be disclosed. Discuss vehicle access and actual school or work trips. The price depends on insurer rules and the household’s application.
Ask about any available good-student or driver-training discount and the proof required. Review liability, PIP and UM/UIM choices along with vehicle use. Keep insurance questions separate from the driver’s license restrictions and household driving rules.
Visit teen-driver guidance for deeper guidance on covering young drivers.
Keeping Olympia Car Insurance Affordable Without Cutting Protection
Compare coverage and total cost together. A clean driving record is one factor an insurer may consider, but it does not guarantee the lowest premium. Review changes in household drivers, mileage, vehicles and selections before comparing a renewal with new proposals.
Smart Ways to Lower Costs
Review the actual coverage and cost when:
-
A vehicle is paid off and aging-you may reconsider collision and comprehensive
-
You change commutes or move within Thurston County, which may change your ZIP code rating
-
Household composition changes-marriage, divorce, roommates leaving or arriving
A higher deductible may reduce a quoted premium but increases the amount retained on an applicable claim. Compare actual prices, lender restrictions and savings available for a loss. Safe driving remains important regardless of whether a particular discount is available.
Defensive driving courses can also help-some insurers recognize these for premium reductions. Ask your insurer or agent what’s available.
Discount Categories to Ask About
Discounts vary by insurer and eligibility. Categories worth asking about include:
-
Multi-vehicle and household policies: Insuring multiple cars on one policy may reduce per-vehicle costs
-
Multi-policy arrangements: If a discount depends on another policy, confirm availability and compare combined coverage and cost with separate proposals. No fixed savings percentage or lowest total price is guaranteed.
-
Vehicle safety features and anti-theft devices: Advanced safety equipment and theft-deterrent systems may qualify for lower rates
-
Usage-based programs: Review mileage, time and driving-behavior data collected, participation requirements and whether pricing may rise as well as fall. See the OIC usage-based insurance guide.
-
Driving-history discounts: Ask which programs are available and what eligibility and documentation they require. Compare the final premium after all applicable discounts.
WashingtonCarInsurance.com can help explain what may be available from the insurers it works with, subject to eligibility and insurer rules. Visit compare coverage and costs for broader cost-management strategies.
Moving To or From Olympia with a Car
New to Washington or Olympia?
If you’re relocating to Olympia from another state, several steps protect your coverage and legal standing:
-
Coordinate coverage with the insurer during the move. Do not assume an out-of-state policy automatically transfers or end required coverage before replacement acceptance and the effective date are confirmed.
-
New Washington residents generally must obtain a Washington driver license and register vehicles within 30 days, with the license first. Review individual exceptions and steps with Washington DOL.
-
Ensure your liability meets the 25/50/10 minimum-or choose higher limits that match your household’s needs.
Visit moving to Washington for a detailed checklist.
Changing Cities Within Washington
Moving from Olympia to another Washington city-or the reverse-can change your ZIP code rating, garaging risk, and commuting patterns. Update your garaging address with your insurer before or immediately after the move to keep coverage accurate and avoid rating disputes.
WashingtonCarInsurance.com maintains city-specific guidance under Washington city directory that explains nuances in other areas of the state.
Areas We Serve Around Olympia
WashingtonCarInsurance.com focuses on personal auto insurance across Washington state, with particular attention to Olympia and surrounding communities:
-
Olympia: Downtown, Westside, Eastside, South Capitol neighborhood
-
Nearby communities: Lacey, Tumwater, and unincorporated Thurston County addresses
Coverage depends on insurer eligibility and terms. Provide accurate garaging information for each vehicle. Use the Lacey guide and Washington city directory for related resources.
Compare Olympia Car Insurance Rates With a Clean Driving Record
A clean driving record is one part of an application. Different age groups, vehicle choices, annual mileage and household driver arrangements can produce different quotes. The OIC rate-factor guide explains permitted factors; no age group or record guarantees the cheapest insurance in Olympia.
Use the current declarations page to compare liability, PIP, UM/UIM, comprehensive and collision on equal terms. Match vehicles, regular drivers, garaging and mileage. Record the complete term premium, payment fees and discount conditions rather than comparing only an initial payment.
If considering more than one policy together, compare the combined coverage and cost with separate proposals. Confirm availability and eligibility. A bundle or advertised discount does not establish significant savings for your particular household.
Affordable Coverage and Insurance Costs After an Olympia Accident
Washington uses fault-based liability rules. Under RCW 4.22.005, a claimant’s own fault proportionately reduces compensatory damages attributable to that fault without automatically barring recovery. That rule does not guarantee that every loss will be covered or that a policy limit is sufficient.
Consider the effect of a deductible on an actual covered loss. In a hypothetical $4,000 collision repair claim, a $1,000 applicable deductible leaves $3,000 after the deductible, subject to policy terms and valuation. Compare the premium at different deductible choices and the money you could retain for repairs or replacement.
Before choosing a company, use the OIC complaint comparison tool to review the actual underwriting company. Distinguish submitted from confirmed complaints, consider market share and look at trends. Raw complaint totals alone are not a reliable worst-company ranking.
Frequently Asked Questions About Olympia Car Insurance
These FAQs address the questions that most often delay quote requests or coverage changes for Olympia drivers.
How much car insurance do I really need in Olympia?
Washington’s general liability minimums are 25/50/10 for applicable vehicles, with approved alternatives and specific vehicle exceptions. A serious covered loss can exceed those limits. Compare higher limits and optional protection using equivalent proposals and your household circumstances. See the minimum coverage guide.
How do changing commute or remote-work schedules affect my policy?
Insurers rate different usage types-commute, pleasure, business-and misclassification can cause issues at claim time. If you switch to hybrid or fully remote status, or change jobs with a different commute distance, update your insurer. Accurate mileage reporting ensures your policy reflects your actual risk.
What should I know about Olympia car insurance if my license was suspended and I need an SR-22?
Washington DOL may require an SR-22 filing after certain license suspensions or serious violations. DOL-not the insurer-decides how long the SR-22 is required, generally about three years from reinstatement eligibility. Cancelling the policy or letting coverage lapse during that period can cause DOL to re-suspend your license. Visit SR-22 guide and the DOL SR-22 page for details.
Can I get coverage in Olympia if I don’t own a car but borrow or rent sometimes?
Non-owner coverage may fit eligible occasional borrowers or renters without an owned or regularly available household vehicle. It generally does not pay for damage to the vehicle being driven. Verify that protection separately rather than assuming an owner or rental company covers every loss. See the non-owner guide.
What happens if my car is in the shop after an accident-will insurance cover a rental?
Rental reimbursement coverage can apply when your vehicle is being repaired under a covered physical damage claim, subject to chosen daily and maximum limits. It does not typically apply to routine maintenance or non-covered losses. A common Olympia scenario: your vehicle is at a local collision center and you need a rental to get to work, school, or state offices. See claims and deductibles for more on repair options, deductibles, and timelines.
Who usually has the cheapest car insurance in Olympia?
No insurer is cheapest for every driver and coverage choice. Compare current equivalent proposals, including full policy-term cost and fees. A city average or another driver’s payment is not your quote.
Is my girlfriend or boyfriend covered when driving my car?
It depends on the policy, permission, household status, frequency of use and any exclusions. Disclose regular access and ask how the person must be listed. Do not assume every permissive-use situation is covered or that calling a regular driver occasional changes the requirement.
Why did my insurance costs increase despite a clean record?
A clean record is not the only factor. Ask the insurer what changed in the rating, household information, coverage, discounts, fees or base rate. Compare equivalent current proposals before assuming a single cause or switching policies.
What information should I give my insurance company?
Provide accurate required details about drivers, vehicles, garaging, mileage, use and prior coverage or claims. Correct errors promptly. For a claim, distinguish known facts from estimates and ask for clarification when a question is unclear.
Get Started with Olympia Car Insurance
Olympia drivers can maintain affordable coverage by keeping their policy aligned with how they drive and by updating changes promptly. WashingtonCarInsurance.com offers Washington-specific guidance, Olympia-focused examples, and help matching coverage to the way you actually drive and live.
Request a personal auto quote or call 844-348-1313 to discuss Olympia coverage options.
A quote request does not bind coverage. Confirm insurer acceptance and the exact effective date before relying on protection. Actual policy terms and underwriting control.